
OTHER
Why Maya Invested the Same Amount Every Month When Everyone Else Was Waiting
Maya learned that building wealth was less about predicting the perfect moment and more about creating a system she could follow.
6 min read
01The Story
Maya had always imagined investing as a game for people who knew something she did not. They watched financial news before breakfast, tracked market moves during lunch, and seemed to have an answer for every question. She assumed successful investors had a special instinct for knowing when to jump in and when to stay away.
After building an emergency fund and paying down her credit card balance, Maya finally had extra money each month. She wanted that money working for her, but every time she prepared to invest, a new headline made her hesitate. One week, experts warned that prices were too high. The next week, people worried about a possible downturn. Every opinion created another reason to wait.
Months passed. Maya kept the money sitting in her bank account while telling herself she was being responsible. She was not avoiding investing because she disliked the idea. She was avoiding it because she wanted certainty before making a decision.
Then she noticed something about her own behavior. She was not actually searching for information anymore. She was searching for a feeling of safety that never arrived. The market did not offer guarantees, but her own habits were quietly guaranteeing one thing: she would keep waiting.
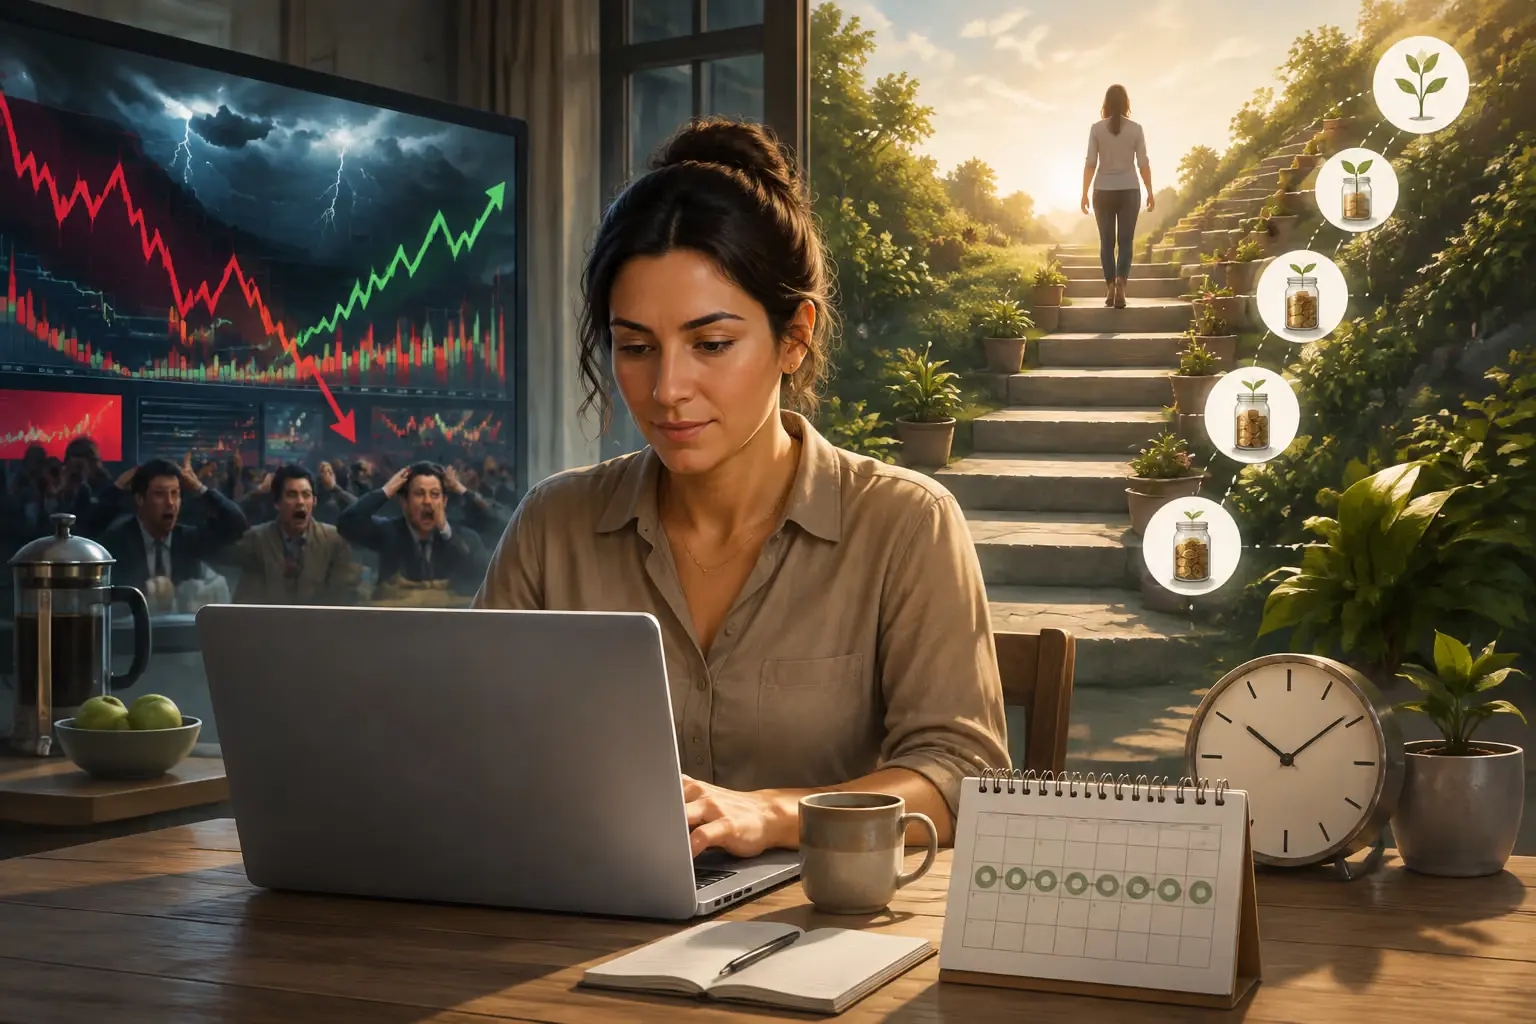
Maya decided to try a different approach. Instead of asking, "When is the perfect time to invest?" she asked, "What investing routine can I continue even when I feel unsure?" She set up an automatic contribution that moved the same amount of money into her investments every month.
At first, nothing felt different. Some months prices were higher. Some months prices were lower. But the biggest change was not in the market. It was in Maya's relationship with uncertainty. She no longer had to make the same emotional decision over and over again.
02What Happened?
Maya had discovered dollar-cost averaging, a strategy built around investing a fixed amount on a regular schedule instead of trying to predict the perfect entry point.
The idea was simple: when prices are higher, her fixed contribution buys fewer shares. When prices are lower, the same contribution buys more shares. Over time, her purchase price becomes an average rather than one single bet made on one specific day.
The strategy did not remove risk. Markets could still rise or fall. There was no magic formula that guaranteed profits. The advantage was psychological as much as financial. Maya created a process that reduced the pressure to make a perfect prediction.
Before, every market headline felt like a personal decision she needed to solve. After automating her contributions, the headlines became background noise. She had a plan, and the plan did not require her to be right every week.
The surprising part was that Maya had been fighting the wrong problem. She thought investing was difficult because she lacked enough market knowledge. In reality, her biggest challenge was managing her own emotions around uncertainty.
03The Hidden Logic
The hidden logic behind dollar-cost averaging is that humans are often better at following systems than making repeated emotional choices.
Money decisions are rarely made in a perfect environment. Fear appears during downturns. Excitement appears during rallies. A person may understand that long-term investing matters, but a sudden market drop can make that knowledge disappear when emotions take over.
A fixed investing schedule creates distance between feelings and actions. Instead of asking, "How do I feel about the market today?" Maya's system asks a different question: "What did I decide when I was calm?"
This matters because timing decisions are harder than they appear. To consistently buy at the best moments, someone has to correctly judge both when markets are expensive and when they are cheap. That requires making two difficult decisions repeatedly. Most people struggle because they are not just analyzing numbers; they are also dealing with fear, excitement, regret, and pressure.
Dollar-cost averaging changes the game. It does not try to predict every movement. It accepts uncertainty and builds a habit around it. The investor gives up the fantasy of perfect timing in exchange for consistency.
There is also a deeper personal finance lesson. Wealth building often depends less on one brilliant decision and more on thousands of ordinary decisions repeated over time. The system matters because the person following it matters.
Maya was not becoming a better investor because she suddenly knew the future. She was becoming a better investor because she designed a process that did not require knowing the future.
04Where You See It
You can see this pattern whenever people delay action while waiting for perfect conditions. Someone waits to invest because the market feels expensive. Someone else waits because the market feels dangerous. Both people may end up making the same mistake: staying on the sidelines for too long.
Many workplace retirement plans use a similar idea. Employees contribute regularly from each paycheck, allowing investing to happen automatically instead of depending on a monthly decision. The power comes from the routine, not from predicting every market move.
The same human challenge appears outside investing too. People often wait for the perfect time to exercise, start a business idea, learn a skill, or make a career change. A system that makes progress automatic can sometimes outperform motivation that depends on feeling ready.
Dollar-cost averaging is especially relevant for people who are building wealth while balancing everyday responsibilities. They may not have hours each week to study markets, but they can create a repeatable process that supports their long-term goals.
The important distinction is that dollar-cost averaging is a strategy for managing timing decisions and behavior. It is not a promise that investments will always increase. The concept works because it helps people stay consistent through uncertainty.
05What You Can Do
Start by separating your investing plan from your daily emotions. Write down your long-term goal and the routine that supports it before the next market headline changes your mood.
Consider whether automation could remove unnecessary decisions. A scheduled contribution can turn investing from a debate into a habit.
Focus on what you can control. You cannot control every market movement, prediction, or news cycle. You can control your preparation, your consistency, and the rules you create for yourself.
Avoid treating a market decline as proof that your plan failed. For a long-term investor using a regular contribution strategy, lower prices may simply mean the same amount of money buys more shares. The meaning of a price change depends on your situation and your goals.
Most importantly, understand your own behavior. If you know uncertainty causes you to freeze, create a structure that reduces the number of emotional decisions you have to make.
06The Takeaway
The smartest money move is not always predicting the future. Sometimes it is building a system that keeps you moving when the future is impossible to predict.
The Takeaway
You do not need to predict every wave to move forward. You need a system that keeps you sailing.